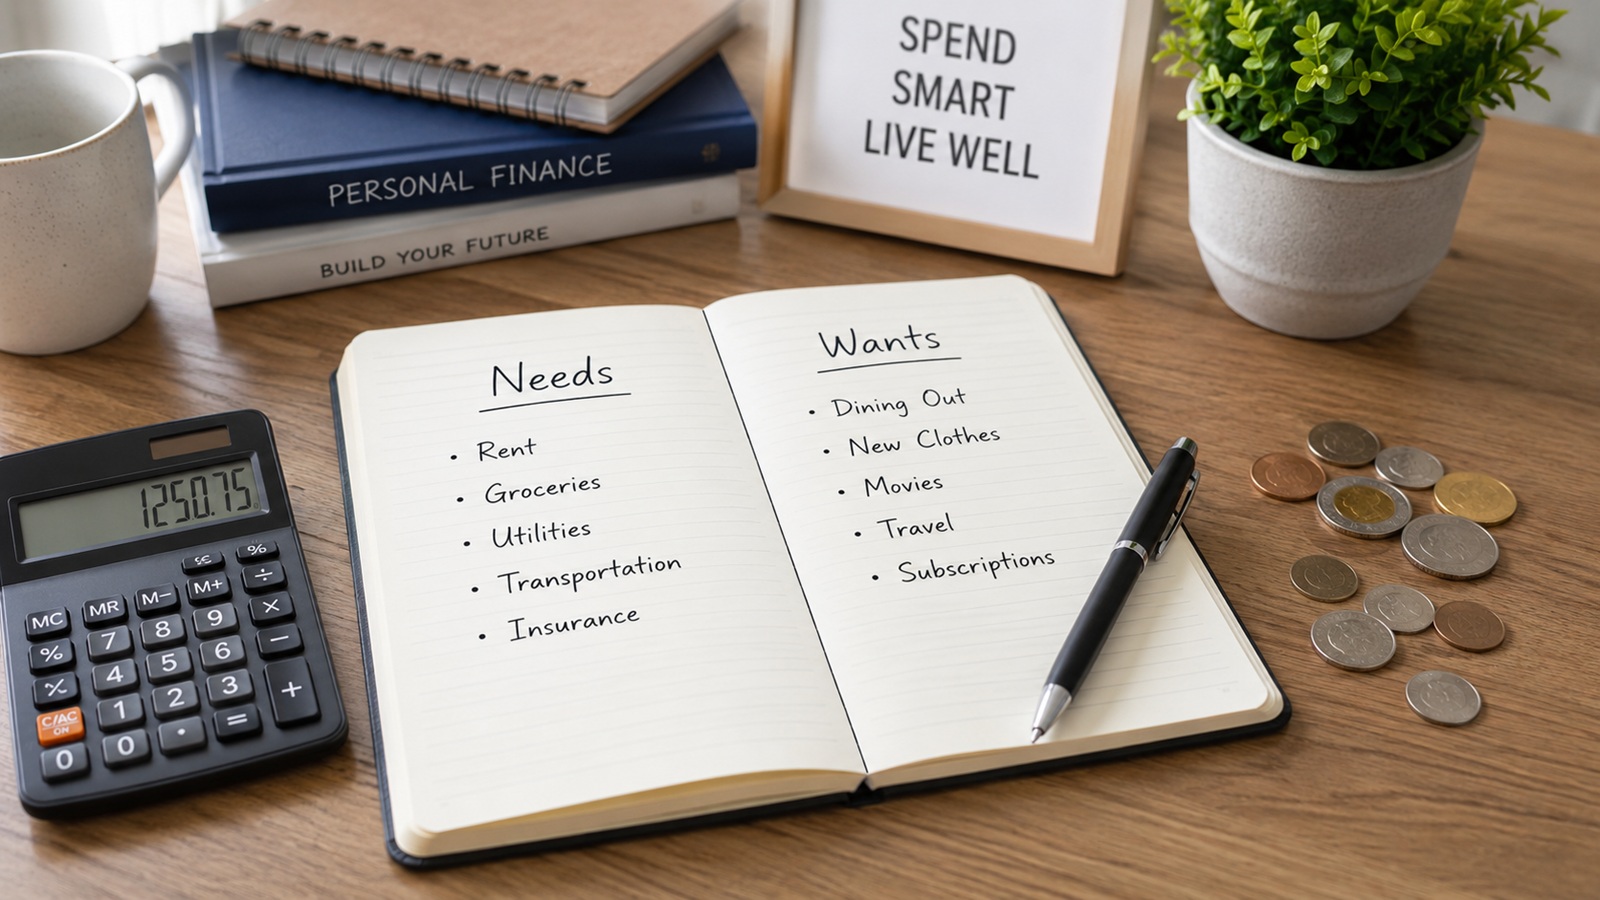
Needs vs Wants: How to Make Better Money Decisions
Understanding the difference between needs and wants is one of the most important lessons in personal finance. Many people struggle with money because they spend on wants before taking care of their needs. This can lead to stress, debt, poor budgeting, and difficulty saving.
A need is something important for daily living. A want is something you may enjoy, but can survive without. Both needs and wants are part of life, but the problem starts when wants take priority over needs.
Learning how to separate needs from wants can help you spend wisely, save more, avoid unnecessary debt, and make better financial decisions.
What Are Needs?
Needs are things that are necessary for your basic life, health, safety, work, education, or family responsibilities. These are expenses that you cannot easily avoid without affecting your wellbeing.
Examples of needs include:
- Food
- Rent or housing
- Basic clothing
- Transport to work or school
- School fees
- Healthcare
- Utilities such as water and electricity
- Basic phone and internet use
- Debt repayment
- Family responsibilities
- Work or business tools
Needs may differ from one person to another. For example, internet access may be a need for someone who works online, studies online, or runs a digital business. For another person, expensive internet bundles used mainly for entertainment may be a want.
The key question is: does this expense support your basic life, work, health, education, or important responsibility?
What Are Wants?
Wants are things that make life more comfortable, enjoyable, or exciting, but they are not necessary for survival or basic stability.
Examples of wants include:
- Eating out frequently
- Expensive clothes
- Latest phone upgrades
- Entertainment
- Luxury items
- Unplanned shopping
- Costly subscriptions
- Frequent travel for fun
- Premium gadgets
- Designer shoes or bags
- Impulse purchases
- Social media lifestyle spending
Wants are not always bad. It is okay to enjoy your money when you can afford it. The issue is spending too much on wants while ignoring needs, savings, debt, or important goals.
Good money management is not about removing all enjoyment. It is about knowing what should come first.
Why the Difference Matters
The difference between needs and wants matters because your income is limited. You cannot spend on everything at the same time. Every financial decision has a cost.
When you spend money on one thing, you may have less money for another. If you spend too much on wants, you may struggle to pay rent, buy food, save, or handle emergencies.
For example, buying expensive shoes may feel good, but if it prevents you from paying school fees or saving for rent, it becomes a poor financial decision.
Separating needs from wants helps you choose wisely.
Needs Can Become Wants
Sometimes a need can turn into a want depending on the cost or situation.
For example, food is a need. But eating expensive meals every day may become a want.
A phone may be a need for communication, work, school, or business. But buying the latest expensive phone when your current one works well may be a want.
Clothing is a need. But buying designer clothes because of peer pressure may be a want.
Transport is a need. But choosing expensive transport every day when a cheaper option is available may be a want.
This is why you should not only ask whether something is useful. You should also ask whether the cost is reasonable.
Wants Can Become Needs
In some situations, something that looks like a want may become a need.
For example, a laptop may look like a want to some people. But for a student, freelancer, teacher, designer, or online worker, it may be necessary.
A course may look optional, but if it improves your job skills or business ability, it can become an important investment.
Good internet may look like a luxury, but for someone working online, it may be essential.
This means the difference between needs and wants depends on your life, goals, income, and responsibilities.
How to Identify a Need
Before spending money, ask yourself:
- Do I truly need this?
- What problem does it solve?
- Can I continue normally without it?
- Is it necessary for my health, work, education, family, or basic life?
- Is there a cheaper option that can still work?
- What happens if I delay buying it?
If the expense supports an important responsibility or prevents a serious problem, it may be a need.
How to Identify a Want
Ask yourself:
- Am I buying this because of pressure?
- Do I want it mainly because others have it?
- Can I survive without it?
- Can I delay it?
- Will it affect my budget negatively?
- Am I using borrowed money to buy it?
- Will I still value it after one week or one month?
If the purchase is mainly for pleasure, image, status, or impulse, it is likely a want.
The Role of Budgeting
A budget helps you control both needs and wants. Without a budget, it is easy to spend emotionally and later regret it.
A simple budget should first cover needs. After that, you can allocate money to savings, debt repayment, and wants.
For example, your budget may include:
| Category | Purpose |
|---|---|
| Needs | Rent, food, transport, utilities, school fees |
| Savings | Emergency fund, goals, future plans |
| Debt repayment | Loans, mobile loans, personal debts |
| Wants | Entertainment, eating out, shopping, hobbies |
This structure helps you enjoy your money without ignoring important responsibilities.
Needs vs Wants in Daily Life
Here are some simple examples:
| Situation | Need | Want |
|---|---|---|
| Food | Buying groceries | Eating out daily |
| Phone | Basic working phone | Latest expensive upgrade |
| Clothes | Work or school clothes | Designer clothes for image |
| Transport | Affordable transport to work | Costly transport for comfort every day |
| Internet | Data for work or study | Extra bundles for endless entertainment |
| Housing | Safe affordable rent | Expensive house beyond your budget |
These examples show that the same category can include both needs and wants.
Why People Confuse Needs and Wants
People often confuse needs and wants because of emotions, peer pressure, advertising, and social media.
Advertisements make products look necessary even when they are optional. Social media can make people feel behind in life if they do not own certain things. Friends and colleagues may also influence spending decisions.
Sometimes people also justify wants as needs because they do not want to feel guilty.
For example, someone may say, “I need this phone,” when the real reason is, “I want to look successful.”
Being honest with yourself is an important part of financial discipline.
How to Control Spending on Wants
You do not have to remove wants completely. Instead, control them.
Here are simple ways to manage wants:
- Set a monthly limit for wants
- Wait 24 hours before buying non-essential items
- Avoid shopping when emotional
- Unfollow pages that encourage impulse spending
- Compare prices before buying
- Avoid borrowing for wants
- Reward yourself only after meeting important goals
- Keep savings separate from spending money
These habits help you enjoy life without damaging your finances.
Use the 24-Hour Rule
The 24-hour rule is simple. When you want to buy something that is not urgent, wait for at least 24 hours before buying it.
This gives you time to think clearly.
After 24 hours, ask yourself whether you still need the item. Many times, the desire will reduce. This helps prevent impulse buying.
For expensive purchases, you can wait longer, such as one week or one month.
Avoid Borrowing for Wants
Borrowing for wants is one of the fastest ways to create financial pressure.
Taking a loan for entertainment, fashion, social events, betting, impulse shopping, or unnecessary upgrades can lead to debt stress.
If something is not urgent or necessary, it is better to save for it instead of borrowing.
Debt should be used carefully and only when there is a clear reason and repayment plan.
Make Saving a Need
Many people treat saving as optional. They save only when money remains. The problem is that money often finishes before anything is saved.
A better approach is to treat saving as a need.
When you receive income, set aside savings first, even if the amount is small. This helps you build discipline and prepare for future needs.
Savings can help you handle emergencies, pay for planned expenses, reduce debt pressure, and reach financial goals.
How to Make Better Money Decisions
Before spending money, use this simple process:
- Ask whether the item is a need or want.
- Check whether it fits your budget.
- Consider whether there is a cheaper option.
- Think about what you may sacrifice by buying it.
- Avoid rushing the decision.
- Spend only if it supports your priorities.
This process can protect you from regret.
Common Mistakes to Avoid
When dealing with needs and wants, avoid these mistakes:
- Calling every want a need
- Spending to impress others
- Borrowing for lifestyle pressure
- Ignoring savings
- Buying things because they are on offer
- Copying someone else’s lifestyle
- Spending without checking your budget
- Forgetting future responsibilities
- Making emotional purchases
Avoiding these mistakes can help you stay more financially stable.
Final Thoughts
Needs and wants are both part of life. You need money for important responsibilities, but you may also want to enjoy comfort, entertainment, and nice things.
The goal is not to stop enjoying life. The goal is to spend in the right order.
Take care of your needs first. Save something. Manage debt responsibly. Then spend on wants only when your budget allows.
When you understand the difference between needs and wants, you gain more control over your money and make better financial decisions.
Disclaimer
This article is for educational purposes only. It should not be taken as professional financial, investment, tax, legal, or business advice. Always consult a qualified professional before making major financial decisions.